You were stopped at a light on Route 1 in New Jersey when the car behind you didn’t stop. The damage to your bumper looked minor. You felt shaken but okay. Then the next morning you couldn’t turn your head, and by the end of the week your lower back was so stiff you could barely get the kids into the car. A few weeks later, an insurance adjuster calls with a number that sounds reasonable until you add up the physical therapy bills still coming in.
Back and neck injuries are the most common outcome of car accidents, and they’re also some of the most misunderstood when it comes to compensation. They don’t always show up on an X-ray, they can take days to fully appear, and they can linger for months or years. If you’re trying to understand what your claim might be worth, here are the factors that actually move the number.
Why These Injuries Are So Common
Rear-end crashes in particular put enormous strain on the cervical and lumbar spine. According to the Insurance Institute for Highway Safety, neck sprains and strains are the most frequently reported injuries in U.S. auto insurance claims, and the organization launched a new whiplash prevention test in 2026 after only four of the first eighteen small SUVs it evaluated earned a good rating for seat and head restraint protection.
In other words, even modern vehicles vary widely in how well they protect your neck, and a low-speed impact can still cause real, lasting injury.
The Severity and Type of Injury
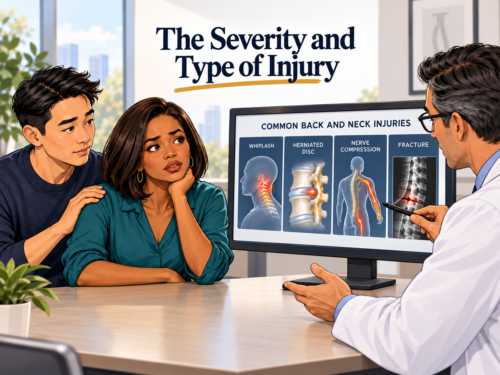
The single biggest factor in any settlement is what actually happened to your body. Back and neck injuries fall along a wide spectrum:
- Soft tissue injuries such as whiplash, sprains, and strains, which typically resolve with rest and therapy
- Herniated or bulging discs that can press on nerves and cause radiating pain, numbness, or weakness
- Spinal fractures ranging from minor compression fractures to unstable breaks
- Nerve damage including sciatica or cervical radiculopathy
- Spinal cord injuries that may cause partial or permanent loss of function
A whiplash injury that resolves in six weeks will settle very differently from a herniated disc that requires surgery and leaves permanent restrictions. The medical diagnosis, supported by imaging and specialist findings, sets the foundation for everything else.
Medical Expenses, Past and Future
Every settlement starts with the cost of treatment. That includes emergency care, imaging, specialist visits, physical therapy, chiropractic care, injections, medications, and any surgery. But it also includes what’s still to come. If a doctor expects you’ll need ongoing treatment, future injections, or eventual surgery, those projected costs are part of the claim. Documenting a clear treatment plan and prognosis is essential to getting future expenses recognized.
Lost Income and Earning Capacity
If your injury kept you from working, the wages you lost are recoverable. If it affects your ability to do your job in the future, whether through permanent restrictions, reduced hours, or a forced career change, the loss of earning capacity can be a substantial part of the settlement. This is especially significant for people in physical jobs where lifting, bending, or standing is unavoidable.
Pain, Suffering, and Impact on Daily Life
Beyond the bills, compensation accounts for what the injury has taken from your life: chronic pain, sleep disruption, inability to play with your children, lost hobbies, and the emotional toll of long recovery. These non-economic damages are harder to quantify but often make up a large share of the total, particularly when injuries are permanent.
Insurers tend to undervalue this category, which is why detailed records of how the injury affects your daily routine matter so much.
Fault and Comparative Negligence
New Jersey follows a modified comparative negligence rule. If you’re found partly at fault for the accident, your settlement is reduced by your percentage of fault, and if you’re more than 50% responsible, you may recover nothing. Establishing clear liability through police reports, witness statements, and evidence from the scene directly affects how much you can recover.
Insurance Coverage and Policy Limits
A settlement can’t exceed the available insurance. If the at-fault driver carries only minimum coverage, that cap becomes a real constraint, and your own underinsured motorist coverage may come into play. New Jersey’s no-fault system also affects which costs are paid by your own PIP coverage versus the other driver’s liability policy, and whether you selected the “limited” or “unlimited” right to sue on your own policy can determine whether you can pursue pain and suffering at all.
Documentation and Legal Representation
Two claims with identical injuries can settle for very different amounts depending on how well they’re documented and negotiated. Prompt medical treatment, consistent follow-up, and organized records establish causation and severity. Understanding local benchmarks matters too.
As Keith Zaid Law explains in its breakdown of the average settlement for back and neck injuries in New Jersey car accident cases, settlement amounts can vary enormously. Minor soft tissue injuries may result in a few thousand dollars, while cases involving surgery or permanent impairment can reach six or seven figures, with outcomes depending heavily on medical evidence and the experience of those negotiating on your behalf. Insurers know which claimants are represented and which are not, and initial offers often reflect that.
Timing and Patience
Settling too early is one of the most common and costly mistakes. Accepting an offer before you’ve reached maximum medical improvement means you may sign away compensation for treatment you didn’t know you’d need. A claim that waits until the full picture is clear almost always resolves for more than one that closes in the first few weeks.
Conclusion
Back and neck injury settlements are shaped by the severity of the injury, the cost of current and future treatment, lost income, the impact on daily life, how fault is assigned, the insurance available, and the quality of documentation and representation behind the claim. No two cases are the same, and the range of outcomes is wide.
What you can control is getting prompt medical care, following through with treatment, keeping thorough records, and understanding your rights before accepting any offer. Handled carefully, a claim reflects the true cost of what you’ve been through rather than the first number an adjuster is willing to say out loud.
Leave a Reply